
Building a Stable Crypto Portfolio for Your Retirement Years
Understanding Ledger’s Role in Retirement Crypto Security
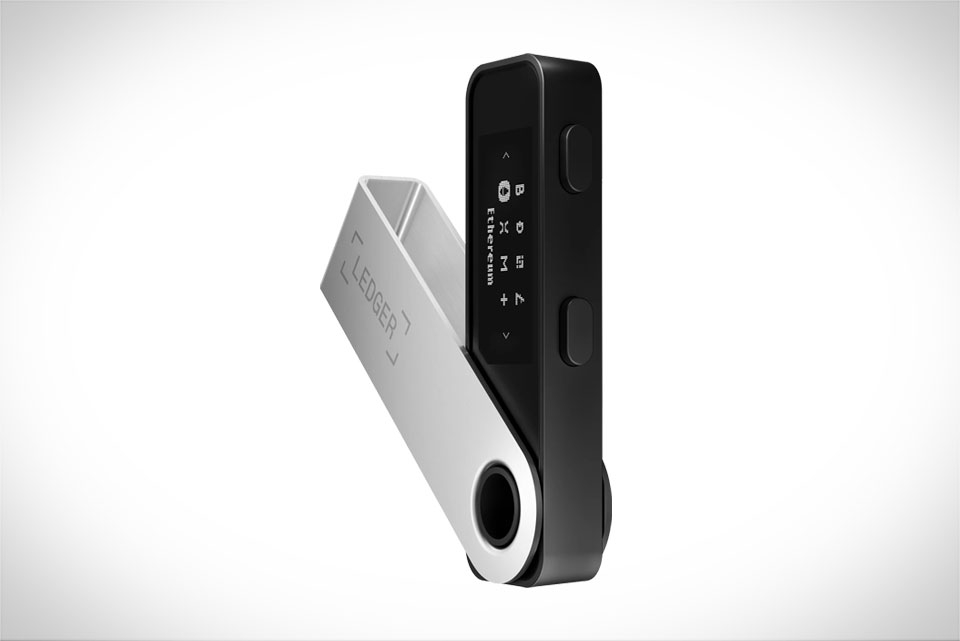
When it comes to retirement savings, security is non-negotiable—especially for crypto, where exchange hacks and platform failures have wiped out millions in recent years. Ledger, a leading hardware wallet provider, solves this problem by keeping your crypto offline in a secure physical device, far from the reach of cybercriminals. Unlike hot wallets linked to the internet or funds held on third-party exchanges, Ledger’s cold storage requires physical confirmation for every transaction, adding an extra layer of protection. For retirement planning, this means your long-term savings won’t disappear due to a single exchange breach, a critical factor when you’re relying on those funds decades from now, as inflation and market swings will test the strength of your portfolio. Many people new to crypto retirement make the mistake of storing all their coins on trading platforms, but FTX’s collapse in 2022 is a stark reminder that unregulated platforms pose massive risks. Ledger’s open-source firmware and seed phrase backup system give you full control over your assets, no middleman to trust with your golden years’ savings.
Structuring Your Crypto Retirement Ledger for Long-Term Growth
A successful crypto retirement ledger isn’t just about security—it’s about intentional structuring for growth and stability over decades. Start by categorizing your holdings into three core buckets: long-term core assets (like Bitcoin and Ethereum, which have proven track records of resilience), moderate-growth altcoins (smaller, established projects with real-world use cases), and emergency stablecoins (USDC or USDT, for unexpected costs). For retirement, aim for a 60-30-10 split: 60% in core assets, 30% in altcoins, 10% in stablecoins. Use Ledger Live, the device’s companion app, to track your portfolio’s performance quarterly, rebalancing as needed to keep your allocation on target. If you’re using a self-directed crypto IRA, Ledger integrates seamlessly with approved custodians, helping you maintain compliance with tax rules while keeping your funds secure. This structured approach ensures you balance growth potential with risk management, a key strategy for retirement planning where volatility should be mitigated over time.
Real-World Case: A Small Crypto Retirement Ledger Setup
Take Mike, a 42-year-old software engineer who started his crypto retirement journey three years ago. He uses a Ledger Nano S, a compact and affordable hardware wallet, to store his savings. Each month, he sets aside $150 from his paycheck to buy 0.002 Bitcoin and 0.005 Ethereum, splitting his contributions evenly between the two core assets. He keeps 10% of his total portfolio in USDC for any urgent expenses that come up. Mike’s Ledger ledger includes detailed records of every transaction: the date, amount, transaction hash, and wallet address, which he uses for tax reporting at the end of each year. He backs up his 12-word seed phrase in two separate physical locations, like a fireproof safe and a family member’s secure storage, so he never risks losing access to his funds. Today, his portfolio has grown to over $18,000, and he feels confident that his savings are safe from hacks or platform failures as he works toward his 67-year retirement goal.
Key Best Practices for Sustained Crypto Retirement Savings
To make your Ledger-based crypto retirement plan work long-term, follow a few critical best practices. First, never share your seed phrase with anyone—this is your only way to recover your funds if your Ledger is lost or damaged. Second, limit the amount of crypto you keep in hot wallets (like Ledger Live’s web interface) to small, active amounts; the bulk should stay offline in the hardware device. Third, adjust your portfolio as you near retirement: reduce altcoin exposure to 10% or less and increase stablecoins to 20% to minimize volatility. Fourth, stay on top of tax rules, as crypto retirement savings have different implications depending on your country—Ledger’s export tool can generate transaction reports that simplify this process. Finally, review your plan annually with a financial advisor who specializes in crypto to ensure it aligns with your changing goals and risk tolerance. These steps help protect your savings while allowing them to grow steadily over the decades.







